Page

Why Your Kenyan Business Can't Claim VAT on Foreign digital services (And How to Fix It)
Why Your Kenyan Business Can't Claim VAT on Foreign Software (And How to Fix It)
The Short Answer (TL;DR): If your business cannot see a foreign supplier's VAT in your auto-populated iTax return, the supplier likely declared their Kenyan sales as an aggregate lump sum. To fix this, you must provide your KRA PIN to the supplier, and they must declare your transaction individually on Sheet B of their VAT return.
Non-resident digital service providers are charging Kenyan customers 16% VAT and remitting it to KRA. Yet, many Kenyan businesses are unable to claim that VAT in their returns.
Say your Kenyan company subscribes to a software platform hosted outside Kenya.
You pay usd1,000 for the subscription and an additional usd 160 as VAT.
The foreign software provider issues an invoice, you pay it, and they confirm the VAT has been paid to the Kenya Revenue Authority (KRA).
But when you go to file your monthly VAT return and download your auto-populated return from iTax, the purchase doesn't appear. You contact the supplier. They insist they paid the tax. You insist you can't claim it. You are officially stuck in a frustrating commercial disagreement.
Interestingly, the problem is not that the foreign supplier failed to file or pay the VAT to KRA. The problem is how they declared the sales in their VAT return.
The Root Cause: Aggregate vs. Individual Declarations
Kenya requires non-resident businesses supplying digital services over the internet to register for VAT and charge 16% on their supplies to Kenyan customers. This applies to both B2C and B2B transactions.
The vat claiming issue happens because there are two ways a non-resident provider can declare these sales:
1. Option 1: The Lump Sum Aggregate (the problem)
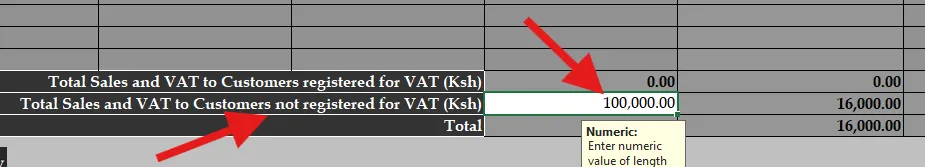
The supplier declares Kenyan sales under 'customers who have not provided a KRA PIN'.
For example, if they made KSh 100,000 in sales, they declare it as one lump sum with KSh 16,000 in VAT. The supplier has paid the tax, but KRA has no individual details to attribute these transactions to specific Kenyan customers.
Consequently, you will not see the purchase in your auto populated return. (see below.)
Instead of reporting all sales as one aggregate figure, the foreign supplier captures the details of each Kenyan business customer, including their KRA PIN, invoice number, and taxable value. KRA can then associate the transaction with your specific PIN, allowing it to appear in your autopopulated VAT return so you can claim your input tax.
What Does KRA Say About This?
This isn't just a workaround, it is KRA's official stance. In their FAQs on the VAT auto-populated return, KRA explicitly addresses this:Can I claim input VAT from Non-Resident Digital Suppliers?"Yes, as long as the Non Resident Digital Supplier has declared your customer PIN on a line item under Sheet B and filed the return. Taxpayers are advised to notify the non-resident digital suppliers that they intend to claim the input so as they are declared on a line item."
A foreign supplier cannot simply aggregate all its Kenyan sales and expect VAT-registered business customers to find their individual purchases in their iTax accounts. They must identify the B2B transactions appropriately.
Action Steps for Kenyan Businesses
Don't wait until the end of the month to discover that the VAT you paid cannot be traced in your iTax account.
Provide your KRA PIN: Give this to the foreign supplier before they issue the invoice.
State your intent: Explicitly inform the supplier that you intend to claim the VAT charged as input tax.
Check your invoices: Ensure your receipt or invoice contains your correct KRA PIN.
Audit your returns: If a purchase is missing from your auto-populated return, contact the foreign supplier immediately and request they investigate how the transaction was declared.
(Note: Appearing in the auto-populated return does not automatically make every purchase deductible. You must still satisfy the general requirements under Section 17 of the VAT Act, including that the purchase is attributable to making taxable supplies.)
Action Steps for Foreign Digital Service Providers
If you are a foreign business supplying digital services to Kenya, you must review how you file your VAT returns to avoid unnecessary commercial disputes with your B2B customers.
Request KRA PINs at onboarding: Ask Kenyan business customers for their PINs if they intend to claim input VAT.
Declare on Sheet B: When preparing your VAT return, declare individual B2B transactions under Sheet B, capturing the customer's PIN, invoice date, taxable value, and VAT charged. Do not lump these into aggregate sales.
Update your invoices: Ensure your invoices clearly show the customer's KRA PIN, the value of the supply, and the VAT charged.
Need Help as a Non Kenyan Business??
ClearTax is the leading digital tax filing provider in Kenya. We can help you with:
✅ iTax Registration – Hassle-free setup with KRA
✅ Tax Assessments – Accurate VAT, SEP, and Withholding Tax calculations
✅ Filing & Reporting – On-time returns filing that keep you penalty free.
✅ Audit Support – Expert defense if KRA comes knocking